Separate assets from production work
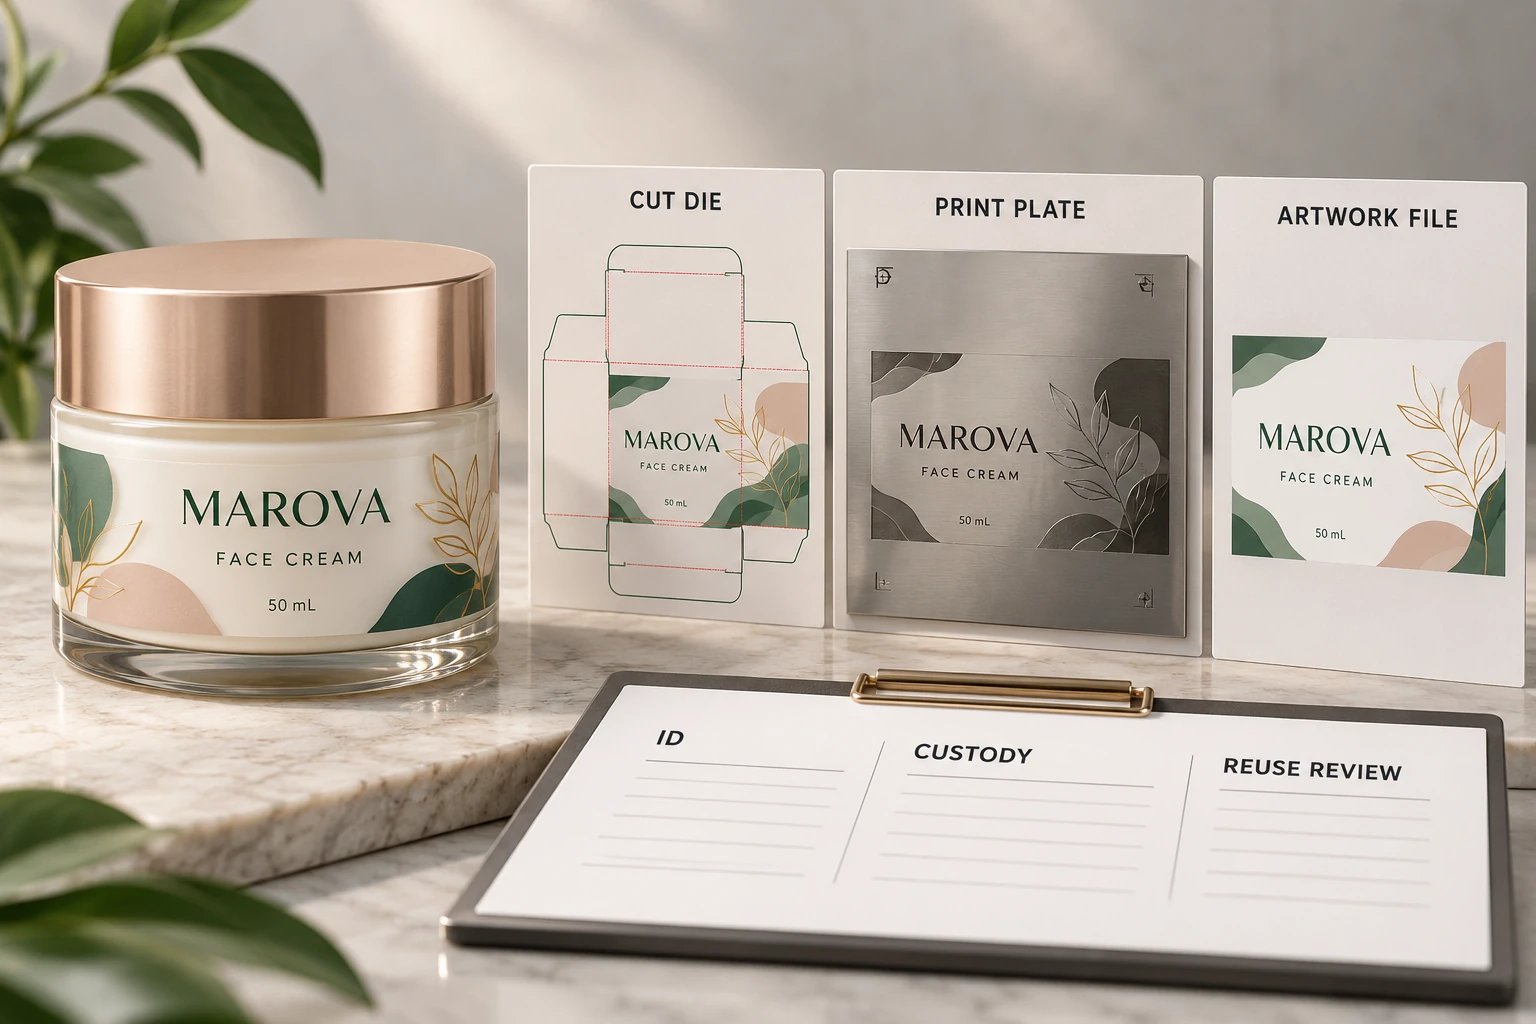
Ask what each original charge covered. A physical cutting tool, a decoration tool, a printing plate and a digital artwork file should not be grouped under one unexplained tooling label. Preparation and machine setup may be activities rather than transferable objects.
Request the relevant asset reference where one exists. Connect it to the artwork revision, dimensions and production route. If the supplier uses an internal tool number, record that cross-reference so a later enquiry can identify the same item.
The digital-versus-flexo quotation guide compares process scope. Here the narrower decision is what existing job assets can be reused and which current services or changes the new quotation actually includes.
Confirm custody and written terms
Ask who holds the asset, whether it remains available and what the existing agreement says about storage, maintenance, reuse and transfer. Read the actual terms or request clarification from the parties responsible for them. This article does not interpret a disputed contract or assign ownership.
Avoid assuming that a file on the brand's computer and an asset in a supplier's production system are the same thing. Likewise, having a copy of a dieline does not establish access to a physical cutting tool made for a particular arrangement.
If ownership or release rights are important to supplier selection, resolve them before ordering. Keep the agreed terms with the job record. A future change of printer is a poor time to discover that everyone attached a different meaning to the first tooling invoice.
Ask what changed in the proposed repeat
Compare the current job with the asset's identified use. Dimensions, artwork features, decorative layers, material or production route can create questions about continued suitability. The technical supplier should determine whether the asset can be reused, needs modification or must be replaced.
Do not infer incompatibility from a new revision number alone. A wording change may affect one production element while leaving another unchanged. Equally, an unchanged logo does not prove that a different size or converting arrangement can use the old tool.
The reorder approval guide locks the intended specification. Use that comparison as the input to the asset review. Reuse should refer to the actual approved job, not a vague instruction to repeat what was printed last year.
Build an asset-and-charge record
The following worksheet helps obtain an answerable quotation. It is not a legal ownership document or a promise that any asset can be transferred.
| Field | Information to obtain | Purchasing use |
|---|---|---|
| Asset or activity | Cut die, print plate, decoration tool, file or setup work | Separates unlike charges |
| Reference | Supplier ID and related job/artwork | Identifies what may be reused |
| Custody | Current holder and availability | Establishes where the asset is |
| Terms | Actual agreed reuse, storage or transfer provisions | Avoids assumptions about rights |
| Compatibility | Proposed job and supplier's technical response | Defines whether reuse is supported |
| Current charge | Itemised new work and quotation scope | Explains what is being purchased now |
| Release | Accepted proposal and unresolved conditions | Connects agreement to the repeat order |
Start with the original invoice and job records. Ask the supplier to map charges to identified assets or activities, then review the proposed job changes. Obtain a current itemised response and reconcile any apparent duplicate before approving the quotation.
If a charge remains unexplained, ask what work it covers and what evidence supports the scope. Do not accuse the supplier of double billing solely because two lines contain the word setup. Equally, a familiar description should not prevent purchasing from requesting a clear explanation.
Different repeat orders can have different justified costs
A hypothetical unchanged job may have an identified available tool and agreed reuse terms. The supplier can explain which preparation or production work still applies and which asset charge does not recur. That makes the quotation assessable without assuming the entire repeat must be setup-free.
A different order may change the label shape or decoration arrangement. Some assets may remain usable while others require review. Asking for an asset-by-asset explanation is more precise than negotiating one undifferentiated tooling amount.
Where another supplier is being considered, obtain its technical requirements and the actual transfer conditions before assuming the existing assets will move successfully. A promised saving is premature until the receiving route and available rights are clear.
For cosmetic label reorders, send the prior job reference, current artwork, dimensions, quantities and the relevant tooling or setup lines. Identify what changed and what needs clarification. The inquiry form prepares a message; send records through email or WhatsApp. Ask for a current proposal that separates reusable assets from the work required for this order.